
Class composition: the first decision that shapes everything
How creditors are grouped into classes is the single most consequential design choice. Creditors whose interests are sufficiently different must vote in separate classes, and getting this wrong can derail a scheme at the sanction stage even after a successful vote.
Class design carries real strategic weight. Each class votes separately, and the approval threshold under section 210 of the Companies Act 1967 is a majority in number representing at least 75% in value of those present and voting in that class. How classes are drawn affects where support is concentrated and where a scheme is vulnerable. It has to be principled, because the court scrutinises it.
Working with the threshold and beyond it
A well-designed scheme is built around the voting arithmetic from the outset: understanding which creditors hold the swing value, and structuring terms they can accept while still delivering a viable outcome.
Where a class is likely to dissent, the IRDA’s cross-class cram-down can, in defined circumstances, bind that class so that a fair plan is not defeated by a single dissenting group. Designing toward a potential cram-down, rather than discovering the need for one later, is part of the craft.
Protecting and funding the process
Two further tools are designed in, not bolted on:
A moratorium
buys the time to develop and vote on a scheme before enforcement action unravels the company. Its timing and scope are part of the plan.
Super-priority rescue financing
can fund the company through the process, and structuring it correctly is what makes a scheme deliverable rather than merely approvable.
Where creditors are already aligned, a pre-packaged scheme, under which the court may approve a compromise without convening a creditors’ meeting, can compress the timeline substantially. A pre-pack rewards careful preparation: the alignment has to be real and demonstrable.
Designing for sanction, not just for the vote
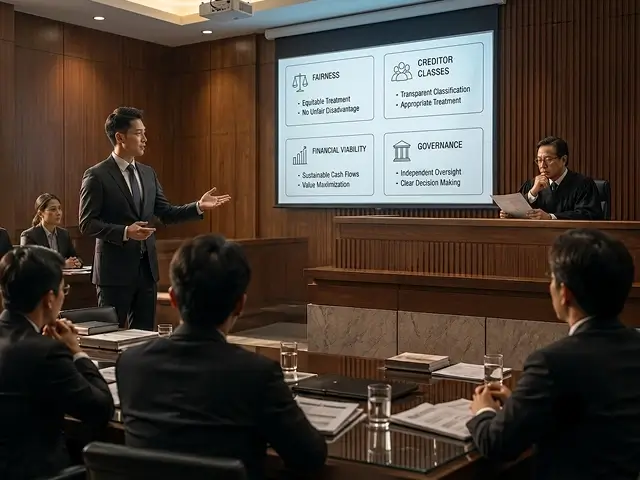
A scheme that wins the vote can still fail at court sanction if the process or the class composition was flawed, or if the deal is not fair to those bound by it. Good design keeps the sanction hearing in view throughout: clean classes, proper disclosure, and terms that a court can be satisfied are fair.
How DHA+ pac approaches scheme design
DHA+ pac brings a practitioner’s eye to scheme design: reading the creditor map early, drawing classes that hold up, and building terms toward both approval and sanction. We have advised on restructurings in Singapore since 1994, and we are candid about when a scheme is the right instrument, or when judicial management or other routes may fit better.
FAQ
Because each class votes separately and the court scrutinises how classes are drawn, getting class composition wrong can sink a scheme at sanction even after a successful vote. It is a principled exercise, not a tactical one.
It is a power that allows the court, in defined circumstances, to bind a dissenting class to a scheme, so a fair, well-supported plan cannot be defeated by one class alone.
When creditor support is genuinely in place in advance. A pre-packaged scheme allows the court to approve a compromise without a full creditors’ meeting, thus compressing the timeline, but ultimately it depends on real, demonstrable alignment.
Legal references: Companies Act 1967 s.210 (voting majority); IRDA s.64 (moratorium), s.67 (rescue financing), s.70 (cram down), s.71 (approval without a creditors’ meeting).
Not sure where to start?
If you are weighing a scheme of arrangement, the design decisions are best made early.
Contact us for a confidential review.